November 18, 2026
VA Loans in Birmingham, AL: Why Now May Be Your Time
Why Today’s Birmingham Market Could Be a Win for Veterans Buying a Home
The quick answer: Yes. If you are a veteran or active-duty service member shopping for a home in the Birmingham area, today’s market may work in your favor. With more homes for sale and more room to negotiate, the benefits of a VA home loan can go even further than they did a few years ago.
And if you have ever heard that buying with a VA loan is harder, slower, or riskier for sellers, there is good news: a lot of what people believe about VA loans simply is not true.
What Is the Birmingham Housing Market Like Right Now?
The Birmingham market has been giving buyers a little more breathing room. According to Redfin, the Birmingham metro’s median sale price averaged $312,229 from January through June 2026, up 4.6% from a year earlier. Active listings were up 3.4%, and the area had about 4.3 months of supply, up slightly from last year. Realtor.com data shows homes in the Birmingham-Hoover area spent a median of 61 days on the market in September 2026.
What does that mean for you? More choices and a little more time to decide. Depending on the home and the neighborhood, that can create room to negotiate on price, repairs, or closing costs, whether you are looking in Hoover, Vestavia Hills, Homewood, Mountain Brook, Trussville, Pelham, Helena, Chelsea, or anywhere across Jefferson and Shelby Counties.
What Are the Benefits of a VA Home Loan?
Alabama is home to roughly 377,000 veterans, and nationwide nearly 4 million service members and veterans have an active VA home loan. According to the Department of Veterans Affairs, more than 343,000 homes were purchased with VA loan benefits in its most recent reported fiscal year. VA loan usage has also grown for two years in a row.
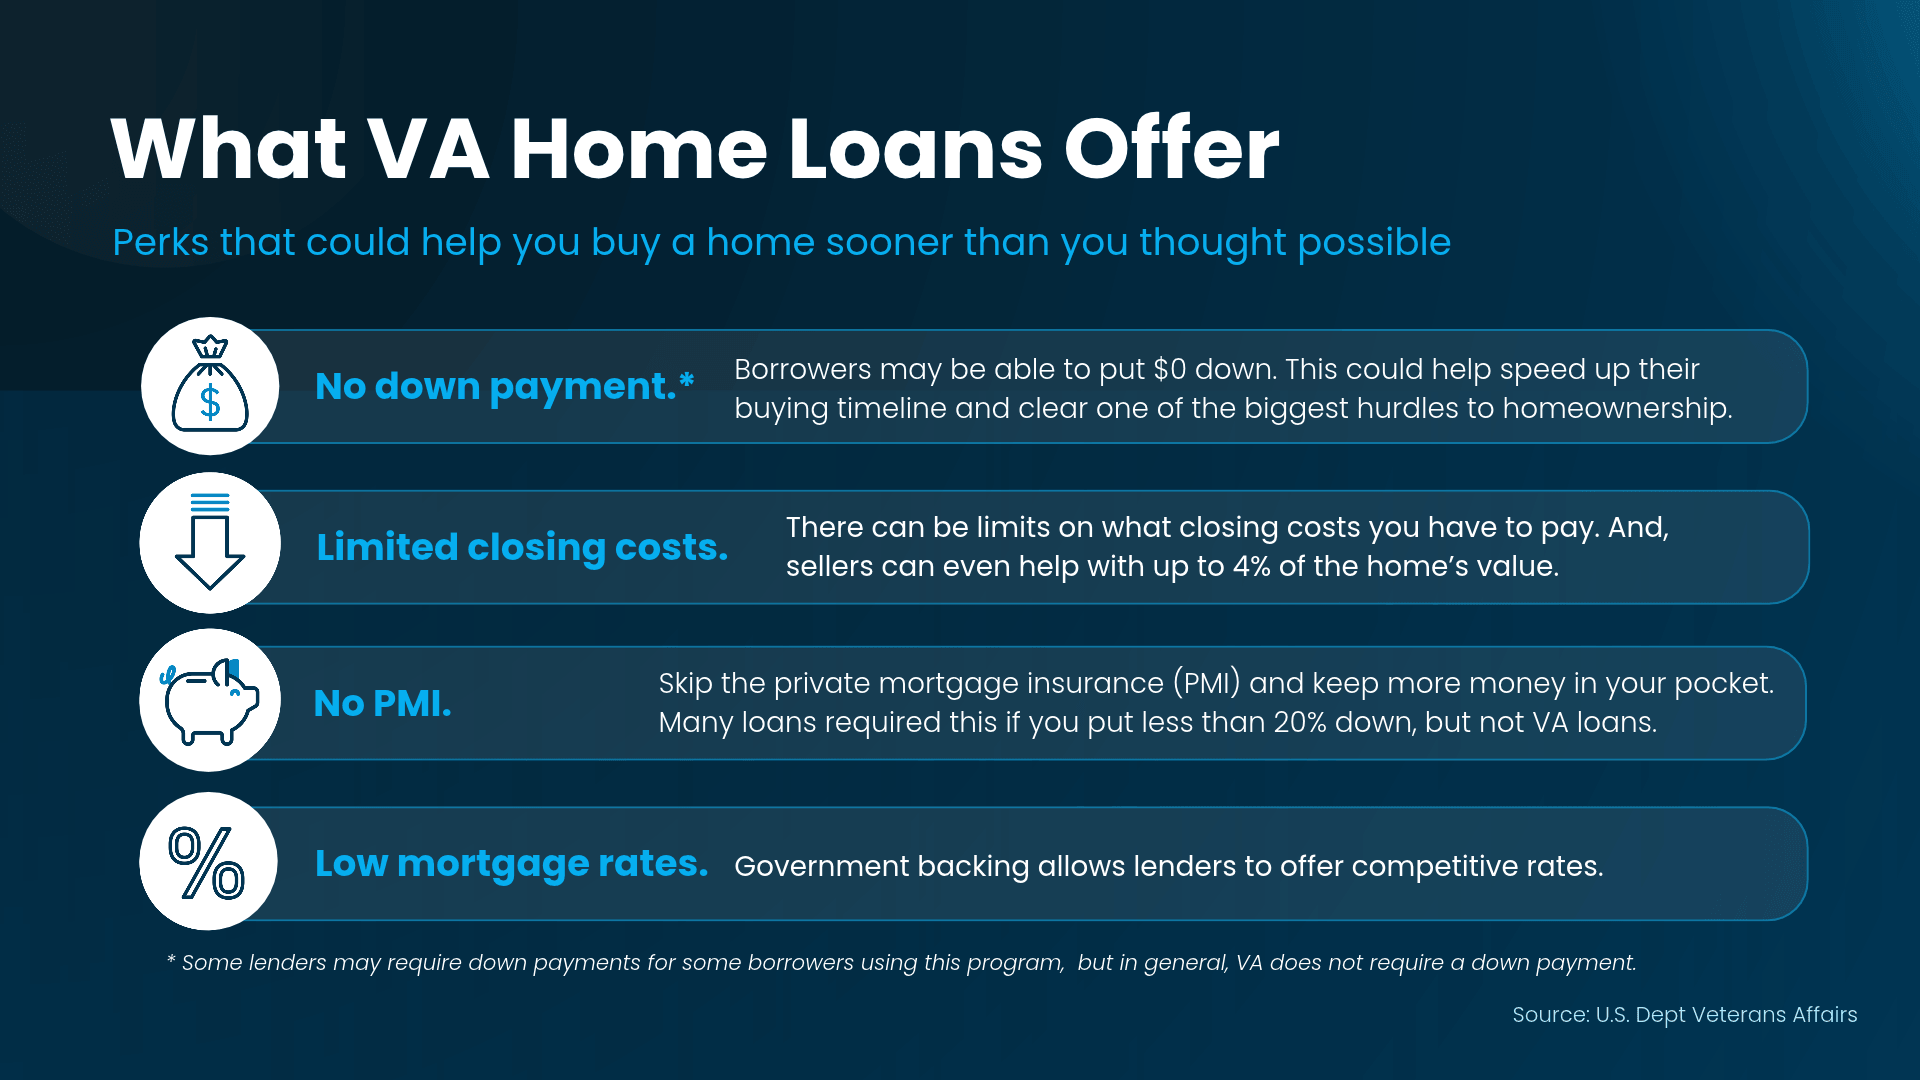
For eligible veterans and service members, VA loans offer advantages that can make buying a home more affordable:
- No down payment required for many eligible borrowers
- No monthly mortgage insurance, even with no down payment
- Competitive mortgage rates that can help lower monthly
Method Mortgage Insight
One more thing to know: VA loans typically include a one-time VA funding fee. It can often be rolled into the loan, and some veterans, including many with service-connected disabilities, are exempt from it. When we sit down together, we will look at your exact situation so there are no surprises.
Do Sellers Turn Down VA Offers?
A few years ago, when homes drew multiple offers and buyers competed for nearly every listing, VA buyers sometimes had a harder time getting an offer accepted. A 2021 National Association of Realtors survey, as reported by the Urban Institute, found that 89% of sellers were likely to accept an offer from a buyer using a conventional loan, but only 30% were likely to accept one from a buyer using an FHA or VA loan.
The reason was a set of worries: that VA financing would take longer, be harder to close, or cost the seller more. Those worries do not necessarily match how VA loans actually perform.
VA Loan Myths vs. Reality
A white paper from Vetted VA, based on 2025 mortgage data, took on some of the most common VA loan myths.
Myth 1: VA loans get denied more often than other loans.
The reality: VA loans had the lowest denial rate. Just 8.2% of VA purchase applications were denied, compared to 15.0% for conventional loans, 12.8% for FHA loans, and 12.5% for USDA loans.
Myth 2: VA financing is less reliable.
The reality: 90% of VA home loan applications that reached underwriting made it to closing, compared to 81% for conventional loans.
Myth 3: VA appraisals take longer.
The reality: VA loan appraisals typically take 7 to 10 business days, similar to conventional and FHA loans.
Myth 4: Sellers have to pay all the closing costs for VA buyers.
The reality: VA buyers can pay many standard closing costs themselves. Buyers and sellers can also negotiate which eligible costs the seller will cover.
Bottom line, much of the earlier concerns from sellers weren’t based on accurate information.
How Much Leverage Do VA Buyers Have Today?
With more homes for sale and fewer buyers competing in many areas, sellers may be more open to different financing options than they were a few years ago. And the opportunity does not stop at getting your offer accepted. Depending on the house and your local market, you may be able to negotiate a lower price, ask for repairs, or request help with closing costs.
VA guidelines allow sellers to cover the buyer’s normal closing costs, plus concessions of up to 4% of the home’s value.
Think about what that combination could mean. You may be able to buy with no down payment, avoid monthly mortgage insurance, and negotiate help with other expenses that come with buying a home. That could mean keeping thousands of dollars in your savings instead of spending them upfront, giving you more breathing room after you get the keys.
Frequently Asked Questions
Can I use a VA loan to buy a home in Hoover, Vestavia Hills, or Homewood?
Yes. VA loans can be used for eligible homes across the Birmingham area, including Hoover, Vestavia Hills, Homewood, Mountain Brook, Trussville, Pelham, Helena, Chelsea, and throughout Jefferson and Shelby Counties. The home needs to meet VA property requirements, and we can help you check that early.
Do I need a down payment with a VA loan?
Many eligible borrowers can buy with no down payment, and VA loans do not require monthly mortgage insurance.
Who is eligible for a VA home loan?
Veterans, active-duty service members, and certain National Guard, Reserve, and surviving spouse borrowers may qualify. A Certificate of Eligibility confirms your benefit, and we can help you get one.
How long does a VA appraisal take?
VA appraisals typically take 7 to 10 business days, similar to conventional and FHA loans.
Why work with a Birmingham-area VA lender?
A lender who knows VA loans and the Birmingham market can help you build a strong offer, explain your options clearly, and keep your closing on track.
Bottom Line
If you are active duty, you have served, or you know someone who has, I would love to help you see what you qualify for. Your VA home loan benefit and today’s Birmingham market could be a powerful combination.
Reach out to me, Andrea Hall, at Method Mortgage: 205.451.1365
Andrea@methodmortgage.com
Related Articles
Here We Go
How to Improve Your Credit Score in 2018